Employers' Liability

The cover the law requires the moment you take someone on, paying out if work injures or sickens your team.

What Employers' Liability covers

The moment you take someone on under a contract of service or apprenticeship, the law requires you to hold Employers' Liability. Whether that duty applies turns on how someone works for you, your direction, your equipment, labour only, rather than on what you call them. Our policy then reaches wider than the duty does: its definition of employee takes in apprentices, many labour-only subcontractors and voluntary helpers working under your control. If a member of your team is injured or made ill by their work, it pays the compensation and the legal costs, so it never comes out of the business. The limit is £10 million as standard, double the £5 million minimum the law sets.

Employee claims

Compensation for employees, apprentices and many contractors.

Injury & illness

Harm or work-related illness caused by their work.

Legal defence

Defence costs for covered claims.

£10m as standard

Double the £5m statutory minimum.

Working abroad

Employees on short business trips overseas.

Prosecution defence

Health & safety and corporate manslaughter defence.

This is a summary of cover. See the FAQ for what's not covered.

Employers' Liability in the real world

A few everyday situations where the cover steps in.
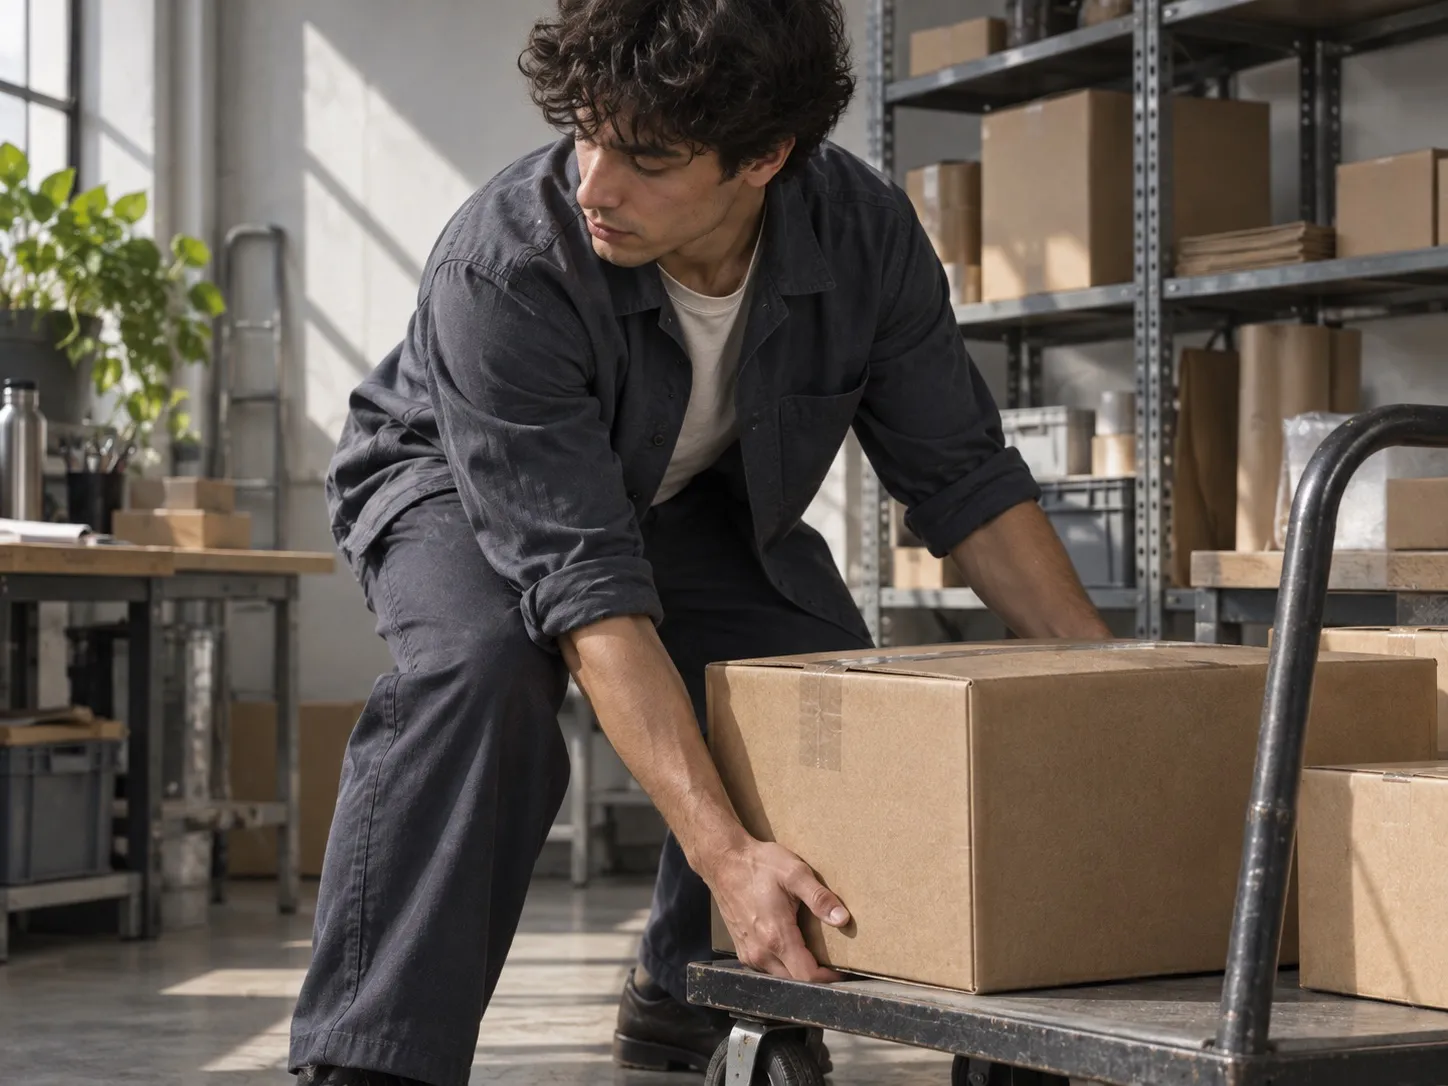
An employee injures their back lifting stock in your warehouse.

Their compensation claim and your legal defence costs are both covered, so a workplace accident doesn't turn into a bill the business absorbs.
A former employee develops a work-related illness years after leaving.

Cover responds to the claim even long after they've moved on, because it's triggered by when the work happened, not when the claim arrives.
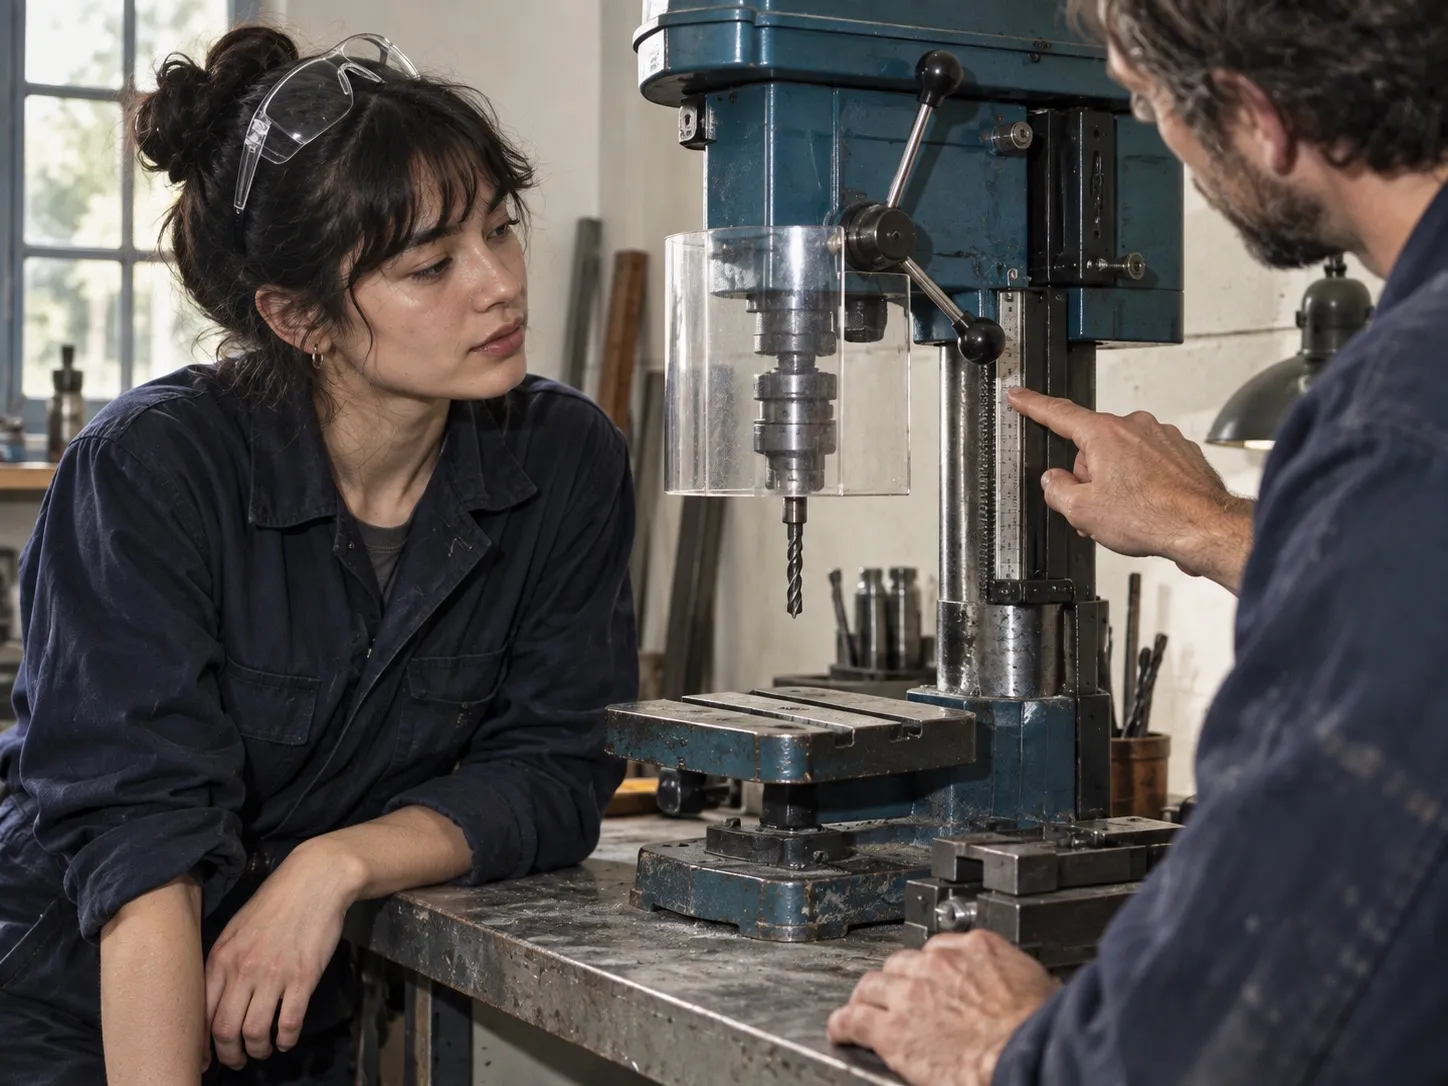
An apprentice is hurt using machinery they weren't trained on.

Apprentices count as employees for this cover, so their claim and your defence costs are handled the same as any other member of staff.

Built for businesses like yours

If you employ anyone at all, from full-time staff to apprentices and most casual or contract workers, Employers' Liability is a legal requirement from day one. What makes someone an employee is how they work for you, not their job title.

Anyone who employs staffShops & hospitality with a teamTrades with apprentices or labourersOffices & agenciesCare & cleaning providersSalons & studios with employeesBusinesses using casual or seasonal staffFirms with volunteers on site

What Employers' Liability gives you

Keeps you on the right side of the law

Employing someone without cover can mean heavy daily fines for as long as you're uninsured. One policy keeps you compliant from the moment you take staff on.

Protects you if a worker is hurt

If an employee is injured or made ill by their work and brings a claim, your compensation and legal costs are paid, even years after they've moved on.

Covers more people than you'd think

Our policy's definition of employee reaches past the payroll: apprentices, many labour-only subcontractors and voluntary helpers working under your control are all in. That is wider than the group the law compels you to insure.

Part of your package

Employers' Liability comes bundled in these packages, or build your own.

Builder

Growing teams with staff

Adds employers' liability, for when you take staff on.

Policies included in this package:

Scaler

Established teams with premises

Full liability, property and cyber cover for stock, equipment and high-value assets.

Policies included in this package:

The words explained

A quick guide to the insurance terms on this page.

Cover for claims made against you by your own workers who are injured or fall ill because of their work. Claims from clients or the public are covered by Public Liability instead.
More than just salaried staff. For this cover, apprentices, many labour-only subcontractors and voluntary helpers under your control count as employees too, which is a wider group than the law's compulsory-insurance duty reaches.
Physical injury, illness or disease an employee suffers because of their work. It's the thing an Employers' Liability claim is built around.
The most your policy will pay for all claims arising from any one incident. Often called the limit of indemnity.
The lowest cover the law allows for Employers' Liability: £5 million. Our policies are written at £10 million as standard.
An extension that covers a client or principal you work under by written contract for liability arising from your work.

Questions, answered

Almost certainly, yes. UK law requires it as soon as you employ anyone, with very few exceptions, such as a business employing only close family, or a limited company with a single employee who owns most of the shares. The statutory minimum cover is £5 million.

Often, yes, and it turns on how someone works rather than what you call them. Apprentices are included, and so are many labour-only subcontractors who work under your direction with your equipment. Bona-fide subcontractors who run their own business and carry their own insurance usually don't. Voluntary helpers under your control count under our policy's definition, even though they generally don't create the legal duty to insure in the first place. If you're unsure where someone sits, HSE's guide HSE40 sets out the test, and caremate™ asks about it during your quote.

Employers' Liability covers claims from your own workers. Public Liability covers claims from third parties: clients, visitors and the public. Most businesses with staff need both.

You can be fined up to £2,500 for each day you're uninsured, and a further £1,000 if you don't display your certificate when asked. It's one of the few business covers that's a legal obligation.

The law sets a £5 million minimum. Our policies are written at £10 million as standard, which covers what most clients and contracts ask for without you having to think about it.

Employers' Liability covers claims from your own team. A few things sit outside it:

  • Claims from non-employees. That's Public Liability.
  • Permanent or long-term work abroad. Overseas cover is limited to short business trips.
  • Injury to an employee in a road traffic accident. That's covered by motor insurance.
  • Fines or penalties from a prosecution. Only the legal defence costs are covered.

Get covered before you need it.

One application covers Employers' Liability alongside the other modules you need, and caremate™ returns your package and price in minutes. Sort it now, so the next bad day is a claim you make, not a bill you swallow.